MULTAN: The Lahore High Court, Multan Bench, has ruled that a Commissioner Inland Revenue cannot declare a taxpayer’s case selected for audit first and then call for its record under Section 25 of the Sales Tax Act, 1990. The court set aside notices issued to M/s JK Sugar Mills (Pvt.) Limited.
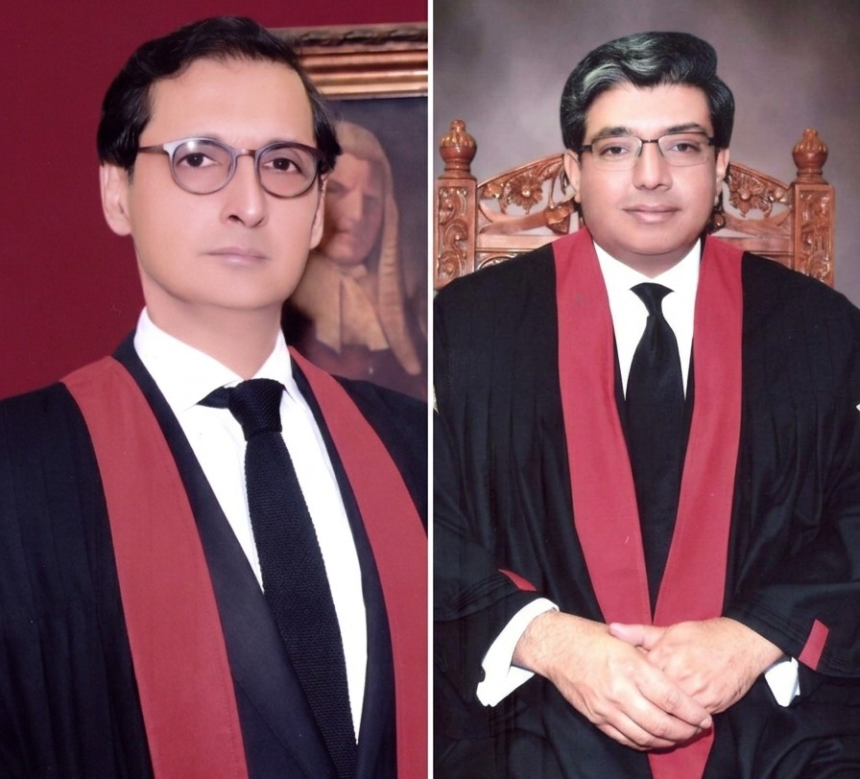
Justice Jawad Hassan authored the 17 pages verdict with Justice Abid H Chatta by holding that the FBR cannot randomly select the tax payer for audit unless it invokes subsection 1 of section 25 of the Sales Tax Act, 1990 before selection under subsection 2.
The Bench heard the case of JK Sugar Mills of Jahangir Khan Tareen former MNA, founder of JDW Group by framing two constitutional moot points then examined the legal anthology of section 25 regarding that whether the Commissioner is vested with unguided or unfettered discretion to invoke section 25(2) by selecting tax payers at will contrary to law as when required rather than as and when desired.
The petitioner, formerly Shamim and Company (Pvt.) Limited, had electronically filed its sales tax returns for all twelve tax periods from July 2015 to June 2016 and discharged its liability after adjusting input tax against output tax. It said it had paid about 91 percent more sales tax than in the preceding year. On 03.03.2017, the Commissioner Inland Revenue notified the company that its case for that period had been selected for audit under Section 25 read with Section 38 of the Act. Three days later, the Deputy Commissioner directed it to produce records including returns, invoices, ledgers, bank accounts, utility bills and production records for audit.
The Division Bench of the Lahore High Court has clarified the procedure for the selection of sales tax audit by the Federal Board of Revenue.
Appearing before the bench, counsel for the petitioner, Malik Ahsan Mahmood, argued that Section 25 merely enables an officer to call for documents and gives no independent power to select a taxpayer for audit. Selection, he said, is governed by Section 72B, under which the FBR selects persons through computer ballot. A general provision, he argued, cannot be used to bypass that mechanism.
Counsel for the respondents, Muhammad Sulaman Bhatti, maintained that the notices were lawfully issued and suffered from no jurisdictional defect. However, the bench framed two questions: whether the Commissioner could select a case for audit under Section 25(2) before issuing a notice under Section 25(1), and whether the phrase “as and when required” confers unguided discretion to select taxpayers at will.
The court held that the two sub-sections are intertwined and complementary. Sub-section (2) permits audit only “on the basis of the record obtained under sub-section (1),” which, it said, creates a direct statutory nexus and a sequence the legislature intended. The Commissioner reversed that order, the court found, by selecting the case for audit on 03.03.2017 and calling for the record only on 06.03.2017. This used sub-section (1) as a later step to justify a decision already taken.
On the expression “as and when required,” the bench said it gives procedural flexibility about timing but does not enlarge the Commissioner’s jurisdiction or dispense with mandatory requirements for selecting a taxpayer for audit. It cannot be used for a roving inquiry or fishing expedition, and reading it otherwise would render the specific audit selection provisions redundant.
The court relied on earlier judgments, including Wazir Ali Industries, Indus Motor Company, Pakistan Telecommunication Company, D.G. Khan Cement and Dewan Sugar Mills. It also cited the Supreme Court’s ruling in Pakistan Beverages Limited (2018 SCMR 1544) that statutory discretion must be exercised reasonably and fairly, along with House of Lords and UK Supreme Court authorities on reading statutory provisions in context.
The bench added that any exercise of power under Section 25 must be supported by a speaking and reasoned order showing why an audit is necessary. This applies particularly where Section 72B already provides a mechanism for audit. The order must also explain the circumstances that justify recourse to Section 25. Resultantly, the court allowed the petition and set aside the notices dated 03.03.2017 and 06.03.2017 in the matter.